
Valuation reset reaches global markets
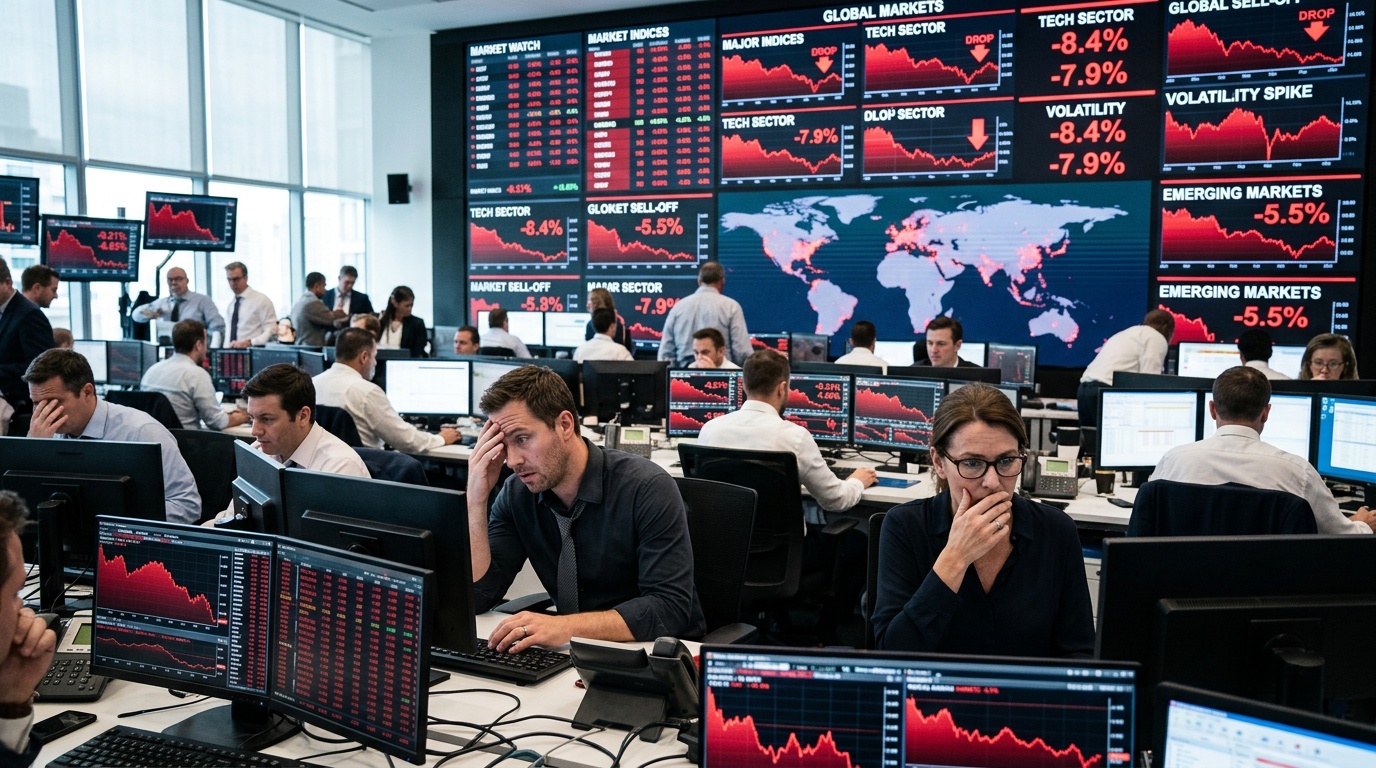
An abrupt retreat in artificial intelligence shares has challenged the market’s most powerful investment theme. Chipmakers, cloud providers, software groups, and data-center suppliers have all faced sharper scrutiny. As prices fell, investors questioned whether expected profits could justify years of aggressive spending. The reassessment spread because AI leaders carry heavy weights in major stock indexes.
That concentration turned a sector correction into a broader global event. Losses among a few giant companies pulled benchmarks lower and weakened appetite for risk. Portfolio managers sold related assets to reduce exposure, meet redemptions, or protect previous gains. Global sentiment now follows the AI investment cycle closely.
Why AI leaders came under pressure
Expectations confront expensive shares
Many leading AI stocks entered the decline with elevated price-to-earnings ratios and ambitious growth forecasts. Those valuations assumed strong demand, durable pricing power, and expanding margins. Any disappointment therefore carried unusual consequences. Even solid results could trigger selling when guidance failed to exceed optimistic expectations.
Profit-taking added pressure after a long period of concentrated gains. Investors had crowded into companies supplying advanced processors, networking equipment, cloud capacity, and electricity infrastructure. When momentum reversed, crowded positioning made exits more difficult. That change pushed attention from revenue growth toward cash generation.
Spending raises harder questions
Large technology companies continue to invest heavily in servers, data centers, and specialized chips. They expect AI services to improve products, attract customers, and create new revenue. However, depreciation, energy costs, and maintenance can weigh on profits before those benefits arrive. Investors now want clearer returns from every additional dollar.
That scrutiny reaches both buyers and sellers of AI infrastructure. Chip suppliers depend on customers maintaining large capital budgets. Cloud groups must prove that usage revenue can outrun infrastructure costs. Software developers must show that AI features support higher prices, retention, or productivity.
Wall Street transmits the shock
The largest American technology companies dominate widely followed indexes. Their scale means a decline can outweigh gains across many smaller shares. Index funds then reflect that weakness, while active managers adjust positions against their benchmarks. The pressure can spread quickly into communications, consumer, and industrial stocks.
Higher volatility also changes behavior in derivatives markets. Options dealers may buy or sell shares as prices and hedges shift. Leveraged investors can cut positions when losses breach internal limits. These actions do not explain every decline, but they can intensify fast moves.
Global markets absorb the pressure
Regional transmission follows industry links
Asian markets feel the shock through semiconductor production and electronics supply chains. Foundries, memory producers, equipment makers, and component suppliers depend partly on data-center demand. A weaker outlook for AI spending can therefore pressure exporters and local currencies. The impact varies according to each company’s contracts and customer mix.
Taiwan, South Korea, and Japan hold important positions across the semiconductor ecosystem. Their markets often react when investors revise forecasts for advanced chip shipments. Chinese technology shares face separate forces, including domestic competition and regulatory policy. Still, global risk aversion can connect otherwise distinct markets.
European indexes contain fewer giant AI platform companies than American benchmarks. However, Europe supplies chipmaking equipment, electrical systems, industrial automation, and data-center components. Banks and luxury groups can also fall when global growth concerns deepen. The sell-off therefore reaches Europe through trade, sentiment, and portfolio allocation.
Bonds and currencies react
The regional effect rarely remains confined to equities. Investors often seek government bonds during sharp risk reductions, which can lower yields. Yet inflation expectations and central-bank policy still shape those moves. Currency reactions depend on rate forecasts, funding needs, and perceived safety.
Market structure amplifies the retreat
Market concentration has increased the influence of several mega-cap companies. Their earnings and capital plans can move entire national and global benchmarks. Passive funds follow index weights rather than conducting independent valuation analysis. However, investors choose when to buy or sell those funds.
Systematic strategies may also respond to volatility, momentum, or risk targets. Some models reduce equity exposure when market swings intensify. Others rebalance after prices cross technical thresholds. These flows can accelerate a decline, although fundamental news usually provides the original catalyst.
Business models face different tests
Uneven challenges shape company performance
The correction does not affect every AI company equally. Chip designers face questions about competition, supply, customer concentration, and product cycles. Cloud providers confront huge capital requirements but also control broad customer relationships. Software companies need less infrastructure, yet they face lower barriers and rapid imitation.
Demand for computing power remains real despite shifting stock prices. Businesses use AI for coding, customer support, advertising, research, and document analysis. Cloud companies report growing interest, while governments support domestic computing capacity. The debate centers on timing, profitability, and the distribution of economic value.
A correction does not equal collapse
A valuation reset does not automatically signal an industry collapse. Falling shares can reflect lower expectations rather than falling revenue. Healthy companies sometimes decline because investors previously paid too much for future growth. Conversely, a lower price cannot repair a weak business model.
Comparisons with the dot-com crash require care. Many current technology leaders generate large profits, hold substantial cash, and serve diversified customers. However, profitable companies can still suffer severe losses when valuations contract. The earlier boom also shows that transformative technologies do not guarantee attractive returns.
The next tests for investors
Earnings, policy, and adoption
Quarterly reports will reveal whether demand supports current investment plans. Investors will track data-center revenue, order backlogs, gross margins, and free cash flow. They will also examine customer concentration and delivery schedules. Management guidance may matter more than historical results during a reassessment.
Interest rates remain central because they influence the present value of future earnings. Higher yields usually create a tougher comparison for long-duration growth shares. Central banks also affect economic demand and corporate financing costs. Meanwhile, export controls and competition rules can reshape accessible markets.
Investors increasingly want evidence that customers gain measurable value from AI. Productivity improvements can support subscriptions, usage fees, or long-term contracts. Pilot projects that never reach deployment cannot justify endless infrastructure expansion. The next phase will reward companies that convert experimentation into recurring profit.
Portfolio strategy shifts after the fall
The decline encourages diversification across sectors, regions, and investment styles. Value shares, defensive businesses, and dividend payers may attract renewed interest. However, diversification cannot eliminate market risk or guarantee positive returns. Investors must still assess balance sheets, competitive advantages, and purchase prices.
Stable earnings guidance could calm markets by narrowing the range of expected outcomes. Evidence of broader AI adoption would also support infrastructure demand. Lower bond yields might ease pressure on valuation multiples. Clearer capital discipline from major spenders could rebuild confidence faster.
Outlook stays tied to execution
The sell-off marks a shift from enthusiasm toward verification. Markets now demand proof that enormous investment will produce durable cash flows. Volatility may persist while companies report results and investors revise assumptions. AI can transform industries, but shareholders still need sensible prices and reliable execution.
