
Wall Street Feels the Rate Reset
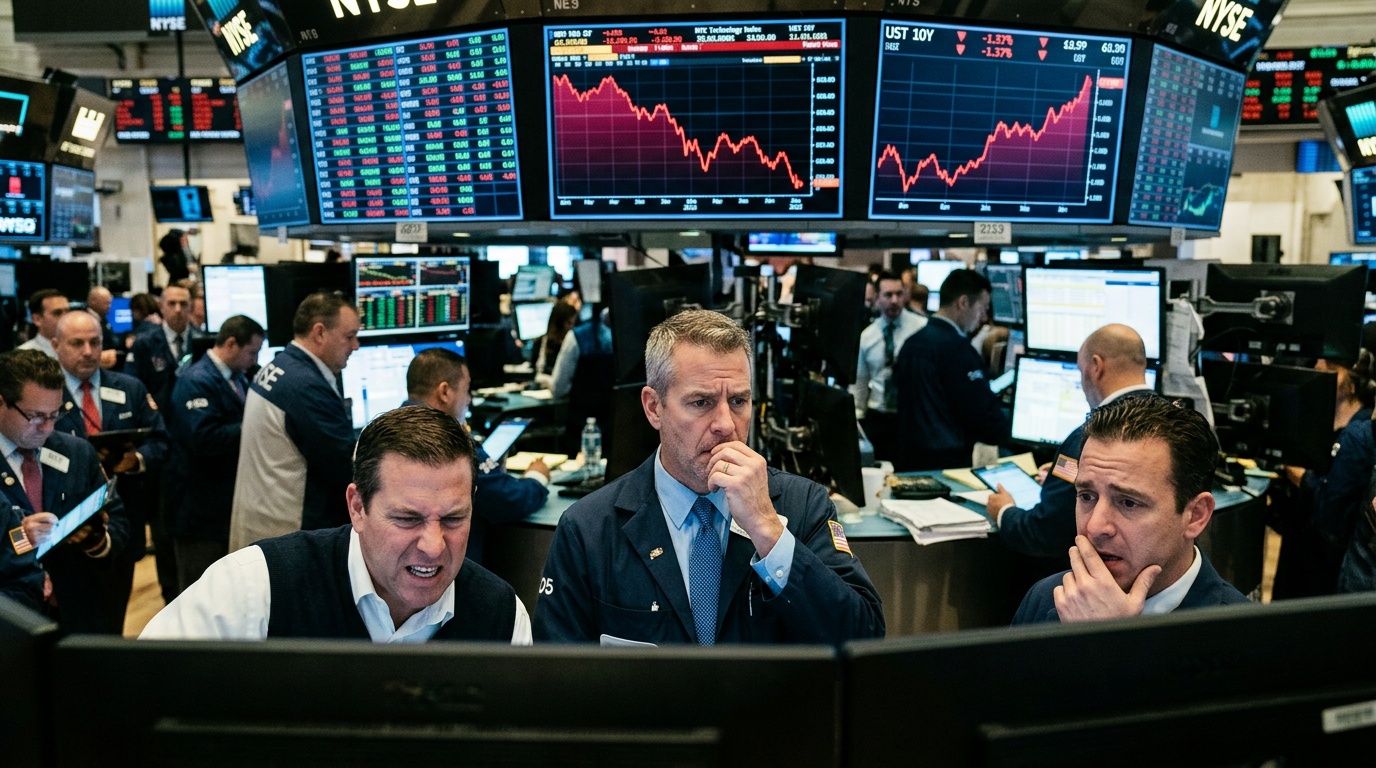
Rising Treasury yields reshape Wall Street’s calculations and weaken the advance in major technology shares. Investors demand greater compensation for government debt, which competes directly with equities for capital. That competition matters because Treasuries offer predictable payments without the earnings uncertainty attached to stocks.
Technology companies feel this shift, especially when valuations depend on profits expected many years ahead. Higher discount rates reduce the present value of those distant cash flows in standard valuation models. As that arithmetic changes, traders often trim expensive positions before questioning the companies’ long-term business strengths. The yield surge therefore changes both financial calculations and market psychology.
Why Treasury Yields Keep Climbing
Bond prices and yields move in opposite directions, so sustained selling pushes market yields higher. Investors may sell Treasuries when inflation appears sticky, economic growth remains firm, or federal borrowing expands. Heavy government issuance can also require higher yields to attract enough buyers at regular debt auctions.
Federal Reserve policy shapes the front end of the curve through its benchmark interest rate. Longer maturities also reflect expectations for inflation, economic growth, and the future supply of government debt. Strong employment or spending data can challenge hopes for rapid rate cuts, lifting yields across maturities. This bond market repricing quickly reaches stocks through borrowing costs and valuation assumptions.
Why Technology Bears the Heaviest Load
Growth stocks command higher earnings multiples because investors expect rapid expansion and substantial future cash generation. When Treasury yields rise, safer assets attract capital, while elevated multiples become harder to justify. Long-duration technology shares remain sensitive because much of their value rests on distant profits.
However, solid results may not support multiple expansion when investors apply a higher discount rate. Profit taking can spread across crowded trades, even when analysts keep forecasts unchanged. The pressure explains why leading technology shares can lose momentum before fundamentals visibly weaken.
Large Technology Companies Shape the Indexes
Major stock indexes give their largest companies substantial influence, especially when those firms carry enormous market values. A retreat among a few technology leaders can therefore pull benchmarks lower despite gains elsewhere. The effect becomes stronger after concentrated rallies leave index performance dependent on a narrow leadership group.
Passive funds do not create this concentration, but their market-weighted designs reflect it automatically. Options activity can amplify daily moves when dealers adjust hedges around heavily traded technology contracts. Meanwhile, equal-weighted indexes may reveal better conditions beneath weak headline benchmarks. That divergence makes market breadth an important test of Wall Street’s underlying resilience.
Higher Rates Create Uneven Sector Effects
Banks can benefit from wider lending spreads, although deposit costs and credit risks may offset that advantage. Insurers may earn more on newly purchased bonds, improving investment income over time. Utilities and real estate companies often struggle because investors compare their dividends with rising bond yields.
Those sectors also rely heavily on borrowing, so refinancing costs can squeeze profits and expansion plans. Consumer companies face another challenge when higher mortgage and credit card rates restrain household demand. Energy and industrial shares may hold up if yields rise alongside stronger economic activity. These differences can broaden market leadership, but they can also expose fresh pockets of weakness.
The Federal Reserve Anchors Expectations
The Federal Reserve controls overnight rates, not longer yields set through Treasury trading. Still, policymakers influence expectations through rate decisions, economic projections, and public comments. A patient inflation stance can keep yields elevated, even when officials see further increases as unlikely.
Conversely, convincing evidence of slower inflation can revive rate-cut expectations and ease pressure on growth stocks. Investors watch core inflation, wages, hiring, and services prices for signs of persistent demand. They also examine whether financial conditions remain tight enough to cool the economy without causing a recession. Each report can shift that balance, producing sharp rotations between bonds and technology shares.
Earnings Must Carry More Weight
When valuation multiples stop expanding, companies need stronger profit growth to support additional share-price gains. Investors then scrutinize revenue guidance, operating margins, customer demand, and spending plans more closely. Technology leaders often generate abundant cash, giving them flexibility to repurchase shares or fund artificial intelligence investments.
Higher yields also raise financing costs for smaller technology businesses that lack established profits. Those firms may reduce hiring, delay projects, or accept less favorable funding terms. The market consequently separates durable cash generators from companies built mainly on optimistic forecasts.
Market Mechanics Can Magnify the Selloff
Rising yields can trigger systematic selling when quantitative strategies respond to volatility, momentum, or changing correlations. Leveraged investors may also cut positions as financing expenses rise and portfolio losses consume risk limits. Exchange-traded funds allow fast sector exits, which can intensify short bursts of indiscriminate selling.
Treasury volatility adds another complication because bonds support pricing and collateral throughout global finance. Rapid yield changes can therefore tighten financial conditions beyond the direct increase in borrowing costs. Once markets stabilize, fundamental investors often return and distinguish stronger businesses from weaker ones.
A Stronger Dollar Extends the Pressure
Higher United States yields can attract foreign capital, which often supports the dollar against other currencies. A stronger dollar reduces the translated value of overseas sales for American multinational companies. Many large technology firms earn substantial revenue abroad, making currency moves relevant to reported growth.
Dollar strength can also tighten global financial conditions because many international borrowers owe dollar-denominated debt. Foreign central banks may face pressure to defend currencies or delay rate cuts. Those responses can weaken overseas demand for hardware, software, advertising, and digital services. Thus, a Treasury selloff can reach technology earnings through channels well beyond domestic valuation models.
Signals Investors Watch Next
Bond traders track inflation reports, labor data, retail spending, debt auctions, and Federal Reserve communications. Equity investors combine those signals with earnings revisions and measures of market breadth. The ten-year Treasury yield receives special attention because it influences mortgages, corporate borrowing, and valuation benchmarks.
Investors also monitor the two-year yield, which reacts closely to expected Federal Reserve policy. A steepening yield curve can signal stronger growth, greater inflation risk, or heavier long-term debt supply. Context matters because the same yield increase can carry different implications for corporate profits. A growth-driven rise may support cyclical shares, while an inflation-driven rise can unsettle nearly every sector.
Managing Risk During a Yield Shock
Investors can reduce concentration by diversifying across sectors, company sizes, assets, and maturity profiles. Diversification cannot prevent losses, but it can limit dependence on a handful of technology winners.
Technology stocks can regain momentum if earnings accelerate or yields stabilize. Until then, Wall Street must balance innovation’s promise against a higher cost of capital.
